Step-By-Step Instructions For Filing Form 1099-NEC
It's common for small businesses to use independent contractors, vendors, and freelancers for projects and other work that can't be achieved in-house. Unlike traditional W-2 employees, who are subject to specific tax rules, nonemployees have their own forms and rules that businesses must follow. If payments meet the reporting threshold, you'll send Internal Revenue Service (IRS) Form 1099-NEC, Nonemployee Compensation, to freelancers and the IRS by the appropriate deadline.
Small business owners who pay contractors and freelancers should use this guide to understand what Form 1099-NEC is, threshold changes for 2026, and how to file.
Key Takeaways
Businesses report nonemployee compensation of $2,000 or more in 2026 (up from $600 in 2025) on Form 1099-NEC.
Form 1099-NEC is due to the IRS and to recipients by January 31st.
E-filing is mandatory once a business files 10 or more combined information returns in a year.
Paper filers must also submit IRS Form 1096, Annual Summary and Transmittal of U. S. Information Returns, as a summary cover sheet.
Late filings trigger tiered per-form penalties that increase the longer a business waits.
A dedicated accountant can track thresholds, deadlines, and e-filing requirements so nothing slips through the cracks.
What Is Form 1099-NEC?
Business owners file Form 1099-NEC with the IRS to report payments made that meet or exceed the threshold. This form can be sent to certain vendors, freelancers, contractors, sole proprietors, and other self-employed workers.
The acronym “NEC” stands for “nonemployee compensation” and means exactly what it sounds like. While Form W-2 is provided to full-time and part-time employees to report, Form 1099-NEC is provided to “nonemployees”, otherwise known as vendors and/or contractors.
In addition to threshold changes, the December 2026 Form 1099-NEC revision renames Box 1 to Box 1a and adds new boxes for cash tips and overtime compensation.
How is Form 1099-NEC different from Form 1099-MISC?
There are more than a dozen different types of Form 1099s. But the two types you will probably encounter the most are Form 1099-NEC and IRS Form 1099-MISC, Miscellaneous Information.
Businesses used to report nonemployee compensation on Form 1099-MISC. Starting in 2020, the IRS began requiring nonemployee compensation to be reported on its own form, Form 1099-NEC.
IRS Form 1099-MISC is still used to report the following types of payments:
Rents of $2,000 or more
Royalties of $10 or more
Gross proceeds paid to an attorney (for example, percent of settlement; attorneys’ fees are reported on Form 1099-NEC) of $600 or more
Crop insurance proceeds of $2,000 or more
Excess golden parachute payments
Fishing boat proceeds (for an individual’s share of the catch)
Fish purchases for cash (when purchasing fish for resale) of $600 or more
Payments of $2,000 or more paid to each physician or other supplier or provider of medical or health care services.
Other 1099 forms are covered in more detail in this blog article. In addition to Form 1099-NEC, you may also require:
IRS Form 1099-K, Payment Card and Third Party Network Transactions: Reports payments received from customers through a third-party payment processor, such as a credit card company or an online platform such as PayPal.
IRS Form 1099-B, Proceeds from Broker and Barter Exchange Transactions: Reports proceeds received from broker and barter exchange transactions. It contains information about stocks, mutual funds, bonds, and other securities.
In an attempt to encourage compliance, the IRS asks the following questions across different tax returns:
Did you make any payments in 2026 that would require you to file Form(s) 1099? (Check ‘Yes’ or ‘No’)
If “Yes,” did you or will you file required Form(s) 1099?
These questions appear on Schedule C (Form 1040), Profit or Loss from Business (Sole Proprietorship), for sole proprietors, IRS Form 1065, U. S. Return of Partnership Income for partnerships, IRS Form 1120-S, U. S. Income Tax Return for an S Corporation for S corporations, and IRS Form 1120, U. S. Corporation Income Tax Return for C corporations.
Who Files Form 1099-NEC?
You’ll need to file Form 1099-NEC for each person you paid at least $2,000 during the course of the 2026 tax year in the following scenarios:
Services performed by someone who is not your employee.
Fees paid to an attorney.
To report sales totaling $5,000 or more of consumer products to a person on a buy-sell, a deposit-commission, or other commission basis for resale.
For each person from whom you have withheld any federal income tax under the backup withholding rules, regardless of the amount of the payment.
It's a best practice to collect IRS Form W-9, Request for Taxpayer Identification Number and Certification, from every contractor before issuing payment, so you already have the TIN and entity type on file.
You only need to report each payment that was made in the course of your trade or business. Personal payments are not reportable.
C corporations and S corporations typically aren’t required to receive a 1099 for payments you make to them because they’re considered separate legal entities. All other non-corporate entities, including individuals and partnerships, should receive a 1099 if you made payments to them during the tax year.
You’ll only issue a Form 1099 for services rendered by an individual (responsible for their own self-employment tax), not for receiving a product.
Form 1099-NEC Filing Instructions
Gather All Information Required
You’ll need the following information to prepare a Form 1099-NEC:
Payer information (this is your business), including your name, address, and TIN (this can be your Social Security number).
Recipient information, including their name, address, and TIN (this can also be a Social Security number).
Payment information. Provide the total amount paid to the recipient during the tax year in question in Box 1a. Record total Federal income tax withheld, if any, in Box 4.
Step-by-Step Guide to Completing Form 1099-NEC
Once pertinent information is gathered, it's time to complete IRS Form 1099-NEC.
Step 1
Enter the total gross amount paid to the contractor (nonemployee compensation) for their services in the calendar year in Box 1a.
Step 2
Check Box 2 if you made direct sales of consumer products totaling $5,000 or more to the recipient for resale. Do not mix nonemployee compensation and direct sales in the same boxes. The IRS intentionally separated these payments.
Step 3
Enter any federal income tax you withheld from the contractor's pay in Box 4. You might check this box because of "backup withholding," which applies if the contractor did not provide a correct TIN.
Step 4
New 1099 updates require specific breakdowns. Report any tips the independent worker received that you processed or distributed on their behalf in the Tip Box, and report specific overtime premium pay if their contract structure includes it in the Overtime Box.
Step 5
Use these Boxes 5-7 to report state-specific earnings and any state income tax withheld, following your local state guidelines.
Choose How to File: Paper vs. E-File
The IRS requires electronic filing for any business filing 10 or more information returns, such as IRS Form 1099-NEC, in a single year. The legacy FIRE system is officially retired. All electronic filers must now use the modernized Information Returns Intake System (IRIS) to submit 1099-NEC forms.
There are 3 different copies of Form 1099-NEC:
Copy A is filed with the IRS.
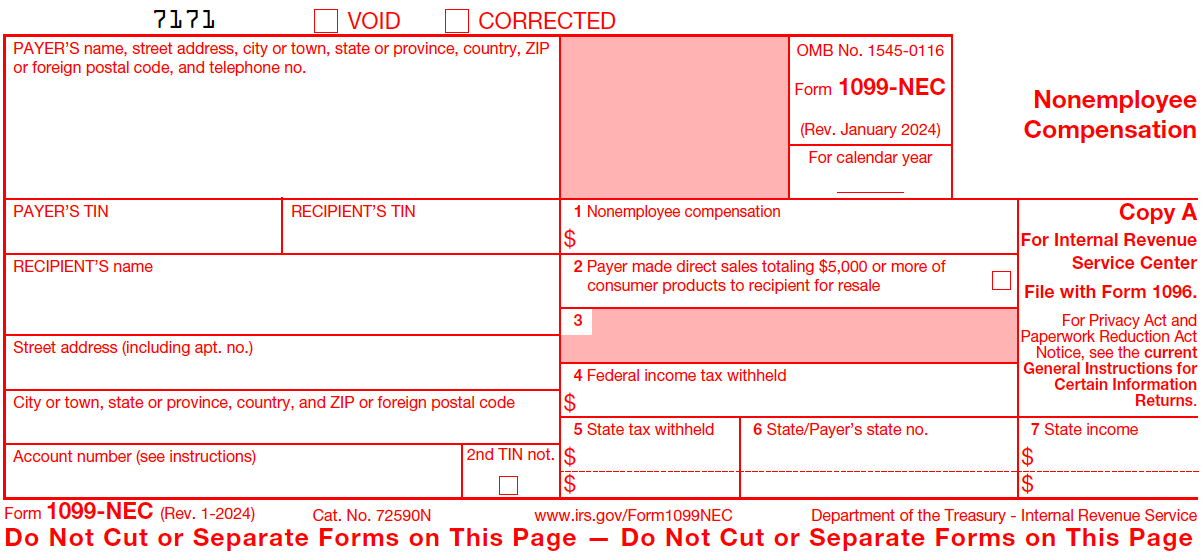
Copy 1 is filed, if applicable, with the state tax department.
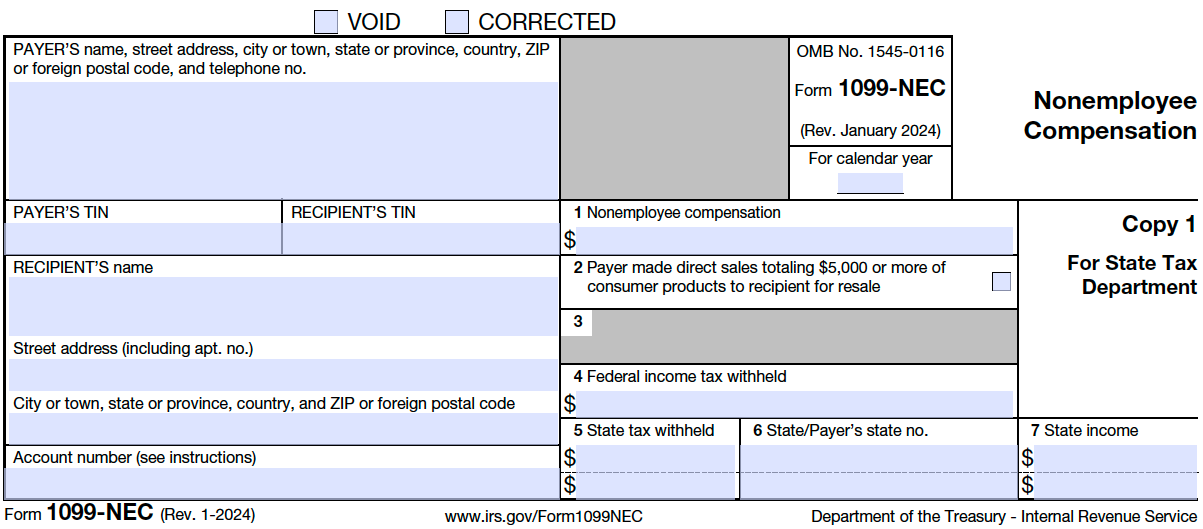
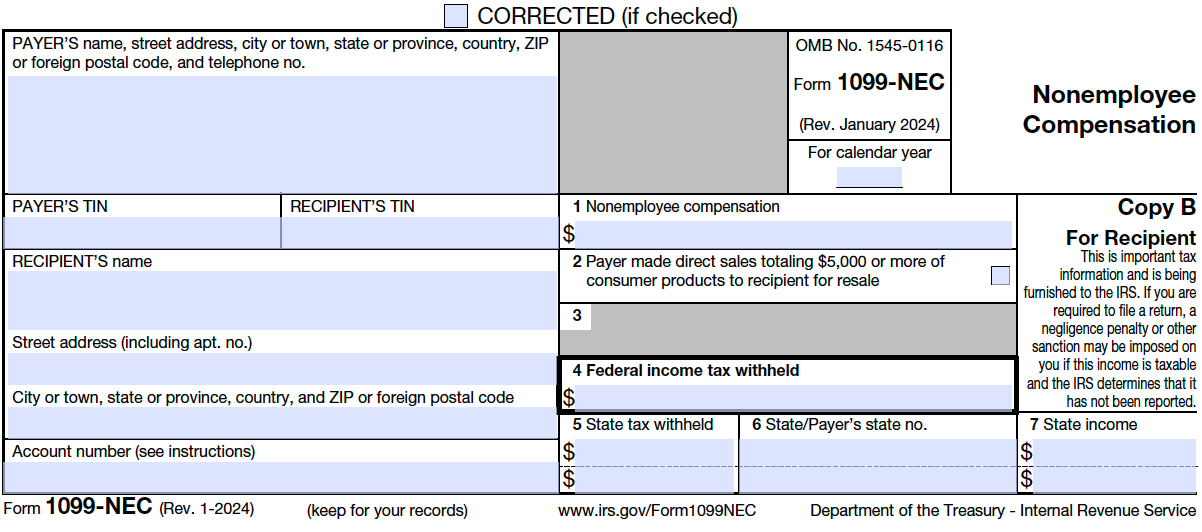
Copy B is provided to the recipient.
You must also prepare and file IRS Form 1096. This form is a summary of all your Form 1099-NECs and should be filed in conjunction with all your prepared 1099-NECs. Be sure that the total dollar amount on Form 1096 matches the combined total of your 1099-NECs.
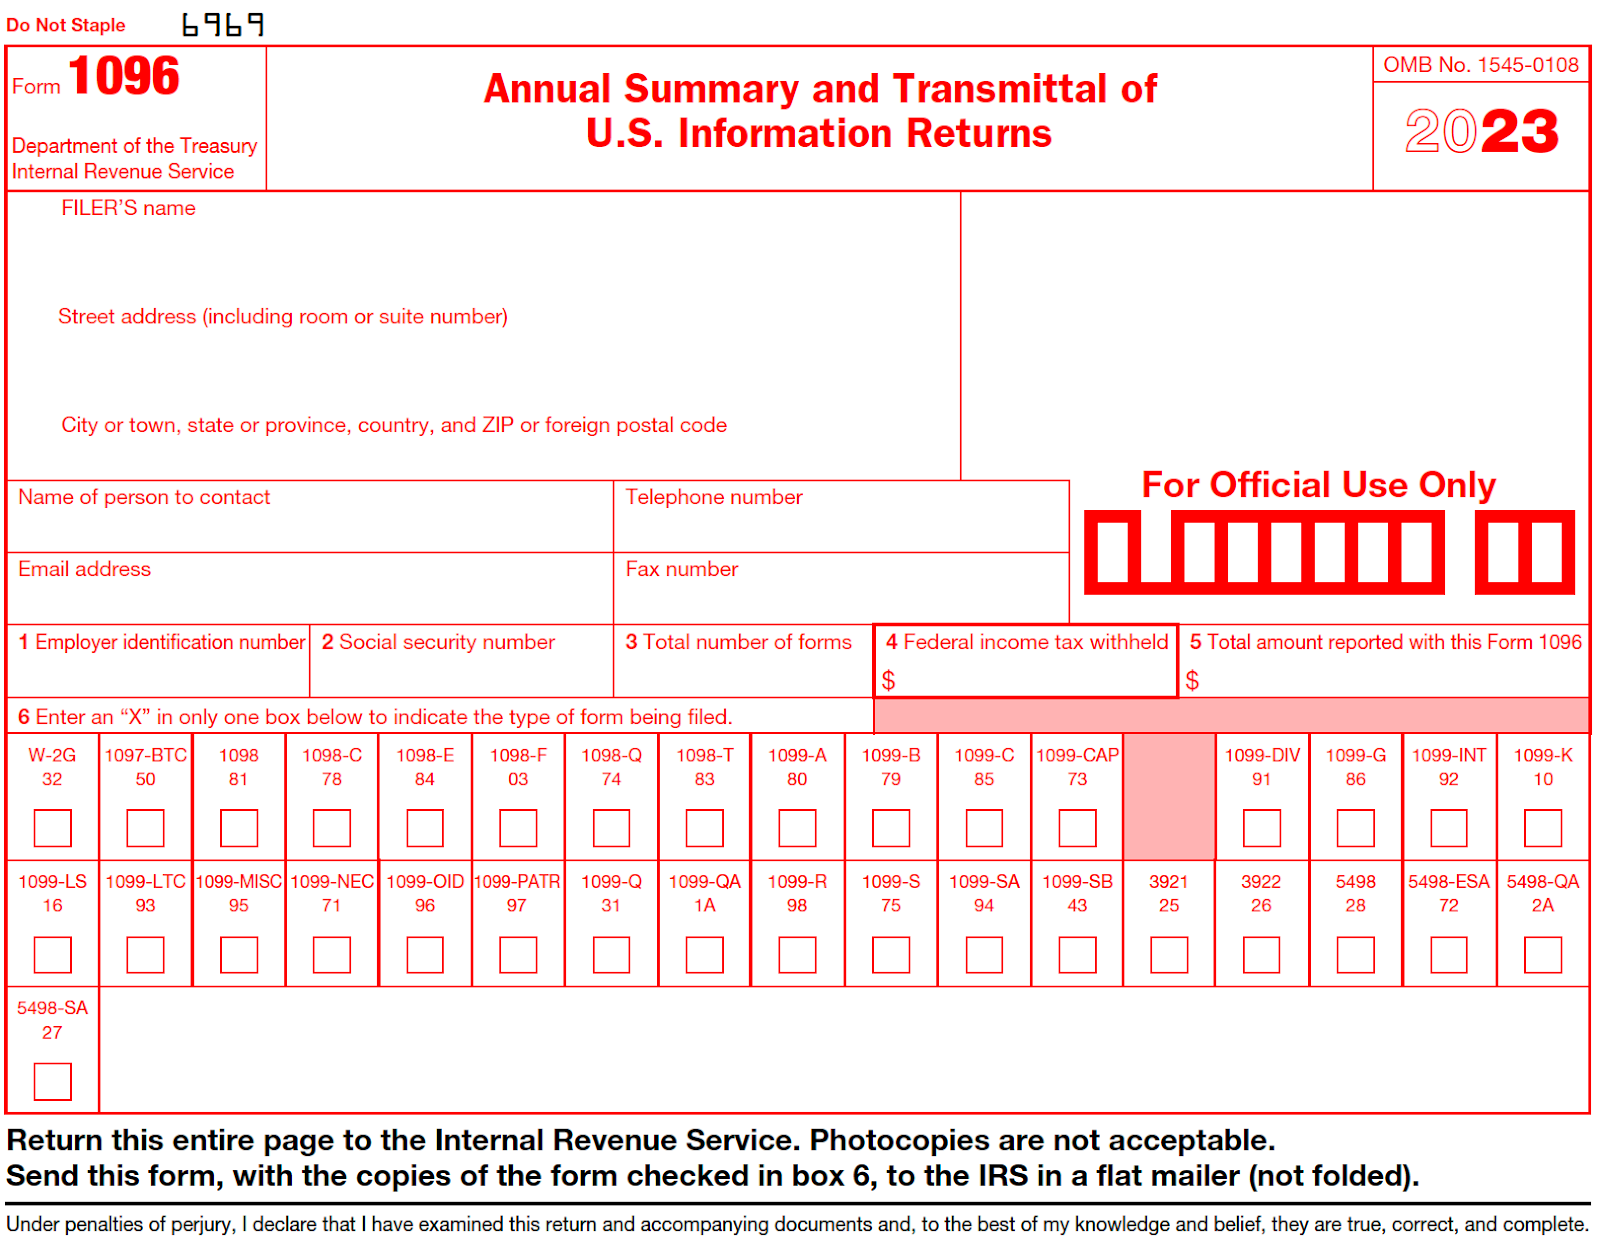
You must include a separate Form 1096 for each type of Form 1099 submitted. DO NOT mix Form 1099-NECs with Form 1099-MISCs.
When and Where to File Form 1099-NEC
Filing Deadlines
Form 1099-NEC should be sent to each contractor and the IRS by January 31st of the following tax year. Deadlines that fall on a weekend or holiday shift to the next business day.
Form 1099-NEC isn't part of the IRS Combined Federal/State Filing Program, so state filing requirements need to be checked separately before proceeding.
Requesting an Extension with Form 8809
Unlike automatic 30-day tax extensions for most informational returns, 1099-NEC extensions aren't automatic. To receive an extension, you must state a hardship reason and file on paper with IRS Form 8809, Application for Extension of Time to File Information Returns.
Form 1099-NEC: Penalties For Late Filing
You may be subject to the following fines and penalties if you’re late filing Form 1099-NEC:
$60 per form if properly and accurately filed within 30 days of the due date. The maximum penalty for small businesses is $249,500.
$130 per form if properly and accurately filed more than 30 days after the due date but by August 1st. The maximum penalty for small businesses is $748,500.
$340 per form if filed after August 1st or if corrections are not filed. The maximum penalty for small businesses is $1,260,000.
$680 per form with no maximum penalty for intentional disregard.
For purposes of the lower maximum penalties, a small business is defined as having average annual gross receipts of $5 million or less for the 3 most recent tax years.
The best way to avoid these fines and penalties is to file your Form 1099-NECs (and all other Form 1099s and tax forms) on time. Ensure you file the appropriate forms by implementing a strong bookkeeping system.
Correcting a Filed Form 1099-NEC
If you notice a mistake after you've prepared Form 1099-NEC, you typically have two main options: voiding or correcting the form.
Voiding an unfiled form means you canceled it but never sent it to the government. Submitting a corrected form means you fixed an error on a form the IRS has already processed. In this scenario, you must then send the recipient an updated copy.
Keeping Contractor Payments Compliant Year-Round
Consistent, accurate bookkeeping can help you efficiently prepare your 1099s and all other required tax forms. This is achieved by ensuring the necessary payment information is entered accurately for each transaction. But when bookkeeping errors increase, or you keep falling behind, professional bookkeeping support can close the gap.
If you're ready for a better bookkeeping experience, explore 1-800Accountant's full-service bookkeeping solution. Up-to-date bookkeeping and easy-to-understand reporting keep your business on track throughout the tax year.
FAQs about Form 1099-NEC
What is the 2026 reporting threshold for Form 1099-NEC?
The 2026 reporting threshold for Form 1099-NEC is $2,000. This means you must issue the form if you pay a nonemployee contractor $2,000 or more during the calendar year. Future limits will adjust each year for inflation.
Do I need to issue a 1099-NEC for payments made by credit card or through PayPal?
No, you do not need to issue a 1099-NEC for these transactions. Payment processors and credit card companies handle this reporting directly using Form 1099-K. A tax professional can identify every form your small business is obligated to file.
What happens if I don't have a contractor's Form W-9 on file?
You are still required to report the payments on Form 1099-NEC even if a Form W-9 is missing. You must start backup withholding at 24% on future payments until they provide their TIN. It's a best practice to always request a W-9 before issuing any payments.
Can I e-file Form 1099-NEC myself, or do I need a provider?
You can file electronically for free using the official IRS IRIS Taxpayer Portal. However, you must first apply online to get a Transmitter Control Code. You can also hire an IRS-approved provider if you prefer guided assistance with managing nonemployee compensation.
What's the difference between Copy A, Copy 1, and Copy B?
Each copy is sent to a different recipient. Copy A is filed directly with the IRS to report the worker's taxable income. Copy 1 is sent to your state tax department for state-level reporting. Copy B is provided to the contractor so they can file their personal tax return.
Does my state require a separate 1099-NEC filing?
Yes, some states require a separate 1099-NEC filing, while others do not require any action unless state taxes were withheld. You should check with your state tax agency for the exact rules. Many third-party filing providers can submit this state data on your behalf.
What should I do if I made a mistake on a 1099-NEC I already filed?
You must submit a corrected form to the IRS as soon as you spot the mistake. You do this by checking the "Corrected" box at the top of a new form. You must also provide the updated copy to your contractor right away.
This post is to be used for informational purposes only and does not constitute legal, business, or tax advice. Each person should consult his or her own attorney, business advisor, or tax advisor with respect to matters referenced in this post. 1‑800Accountant assumes no liability for actions taken in reliance upon the information contained herein.